How to file and pay non-resident tax in Spain with Modelo 210
Responsible for this content: Frank Menze
Own a finca on Mallorca, an apartment in Palma or a holiday home in Playa de Muro – but still spend most of your time living in Germany, Austria or Switzerland? Then you have limited tax liability in Spain and must file a Modelo 210 return each year for Spanish non-resident income tax (IRNR – Impuesto sobre la Renta de No Residentes). This applies even if you have never rented out your property. This guide explains how the tax is calculated, which deadlines you must meet, why EU citizens have a clear advantage over non-EU citizens, and which mistakes tend to prove most costly.
What is non-resident income tax – and exactly who does it apply to?
IRNR is a separate tax that applies only to people who are not tax-resident in Spain but earn income or hold assets there – particularly property. It should not be confused with Spanish income tax for residents (IRPF), which you only have to pay once you have moved your tax residence to Spain.
You are considered a non-resident for tax purposes if you spend fewer than 183 days per calendar year in Spain and your main economic interests are not based there. Temporary absences count towards the 183-day total – so if you only go home occasionally, you should keep careful records of your days.
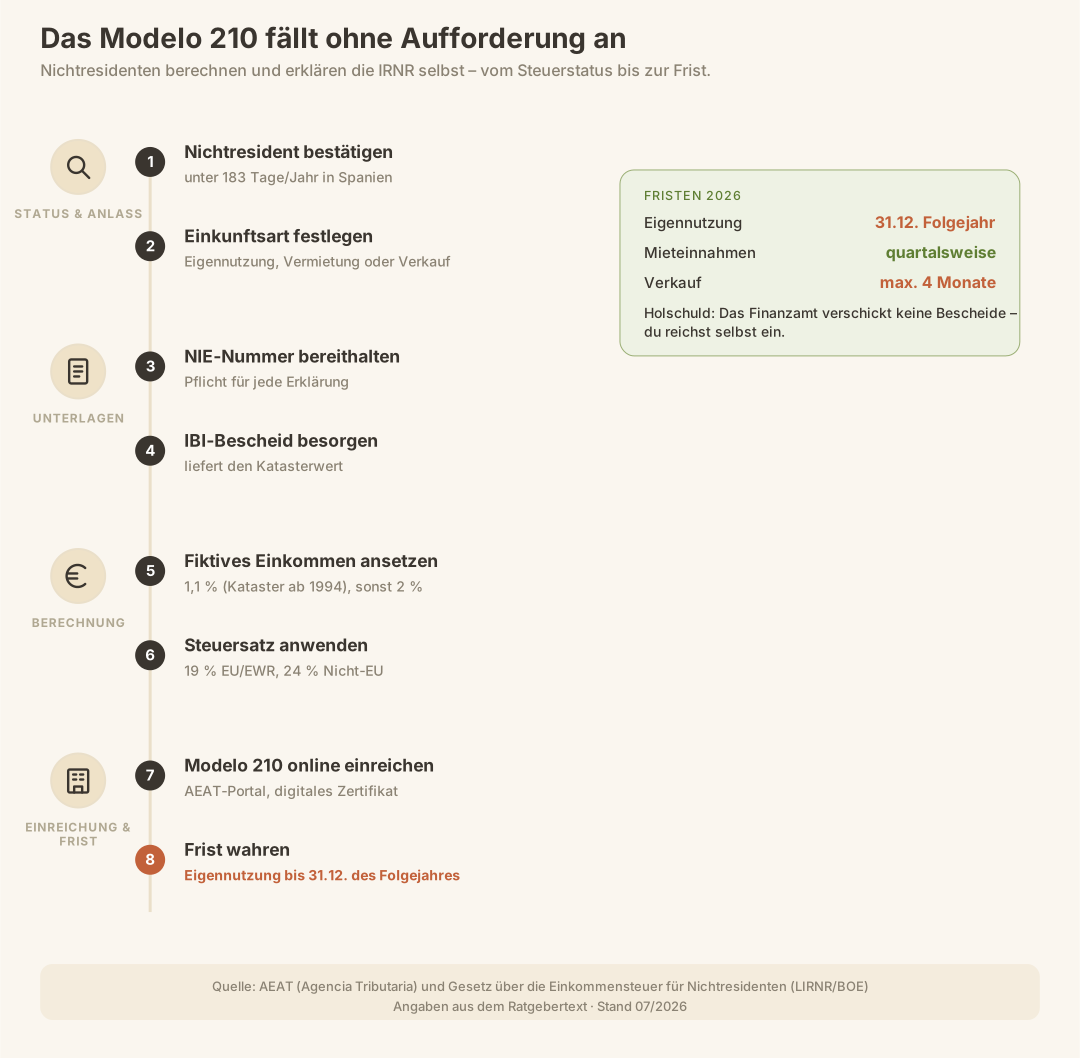
Important: The Spanish tax authority (Hacienda, at national level: AEAT) does not send out tax bills. This is a self-assessment obligation: you must file the return and pay the tax by the deadline yourself – whether or not you have received any reminder.
For property owners, non-resident income tax covers three different scenarios:
Scenario
Type of income
Basis for calculation
Owner-occupied / vacant
Imputed income (Renta Imputada)
Cadastral value (Valor Catastral)
Rental (including holiday lets)
Actual rental income
Net income (EU/EEA) / gross income (non-EU)
Property sale
Capital gain
Sale price minus acquisition costs
Resident vs non-resident: the crucial distinction
Days spent in Spain
days
Explanation
Days of presence are every day you were in Spain, including days between two documented stays unless you can prove you were abroad. Arrival and departure days each count in full.
days
Explanation
Sporadic absences (“ausencias esporádicas” — short trips abroad) are days not included in the figure above. The law adds them rather than subtracting them.
Explanation
A tax residence certificate (“certificado de residencia fiscal”) is confirmation from a foreign tax authority that you are tax-resident there; it is valid for one year. It excludes only sporadic absences, not your presence in Spain.
Based on your entries, neither criterion is met.
Interim result: the calendar year is still in progress.
Total residence days counted
150 days
Statutory threshold (more than)
183 days
150 = 150 days
Days needed to cross the threshold: 34.
Legal status: 1 January 2007
This calculation is provided for guidance only and is not a substitute for tax or legal advice in specific cases.
Before you deal with Modelo 210, you need to establish your tax status clearly. If you incorrectly declare yourself a non-resident when you are already a resident, you risk a retrospective tax assessment with surcharges. It is equally risky to be treated as a resident when Spain is not actually the centre of your life.
Criterion
Tax resident
Non-resident
Time spent in Spain
> 183 days/year
≤ 183 days/year
Centre of economic interests
In Spain
Abroad
Tax return
IRPF (worldwide income)
IRNR (Spanish income/property only)
Main form
Modelo 100
Modelo 210
Anyone who has a Residencia and is registered (empadronado) is generally considered a resident – but must be able to prove how much time they actually spend in Spain. Read more in our guide to Residencia in Spain.
The three scenarios in detail: owner-occupation, letting and sale
Rental income tax
Explanation
Cleaning and linen only at arrival and departure are not hotel-like. In-stay cleaning, reception, meals or luggage service count, including when subcontracted.
Explanation
Total income for the whole property, including items let with it, but excluding Spanish VAT (IVA).
Explanation
Only EU or EEA residents covered by tax information exchange may deduct these costs.
Explanation
Simplified combined amount, treated as already allocated to the letting period; depreciation is not included.
Rental tax per owner
€2,223.00
rendimiento neto (net rental income)
€11,700.00
Gross rent for the whole property
€18,000.00
Legal status: 1 January 2023
This calculation is provided for guidance only and is not a substitute for tax or legal advice in specific cases.
Case 1: Owner-occupation and vacant property – ‘imputed income’
The most surprising aspect of IRNR for many holiday-home owners is that even if you never let your Mallorca property and use it exclusively yourself, Spain attributes an imputed income to you – known as Renta Imputada.
The calculation works as follows:
The starting point is the cadastral value (Valor Catastral) of the property, which you can find on your IBI bill.
Generally, 1.1% is used if the cadastral value was reviewed or updated after 1994; 2% if the last cadastral update was before 1994.
The tax rate (19% for EU/EEA, 24% for non-EU) is then applied to this amount.
Worked example (simplified):
Step
Example figure
Property’s cadastral value
€200,000
Imputed income (1.1%)
€2,200
Tax for EU citizens (19%)
€418
Tax for non-EU citizens (24%)
€528
Note: If you use the property yourself for only part of the year and rent it out for the rest, the imputed income is calculated proportionately – Renta Imputada applies to vacant and owner-occupied periods, while actual rental income applies to periods when it is let.
Modelo 210: personal use
Explanation
The valor catastral is the property's official assessed value. It appears on your IBI bill (local property tax) and is usually well below the purchase price.
Explanation
A transitional rule applies to this tax year: what matters is whether the cadastral value has been revised since 1 January 2012.
Explanation
Your tax residence determines the tax rate. Select whether you live in the European Union (EU), the European Economic Area (EEA) or elsewhere.
Imputed income (renta imputada)Why this figure?
Percentage of cadastral value: 1.1%, apportioned by days and ownership share.
€2,200.00
Tax per ownerWhy this figure?
Tax rate on imputed income: 19%.
€418.00
Total
€418.00
Calculated using an ownership share of 100%.
Tax for the whole property (all owners combined, assuming the same tax treatment)€418.00
Filing window: 1 January 2026 to 31 December 2026 — the whole calendar year still applied to this tax year.
Legal status: 1 January 2023
This calculation is provided for guidance only and is not a substitute for tax or legal advice in specific cases.
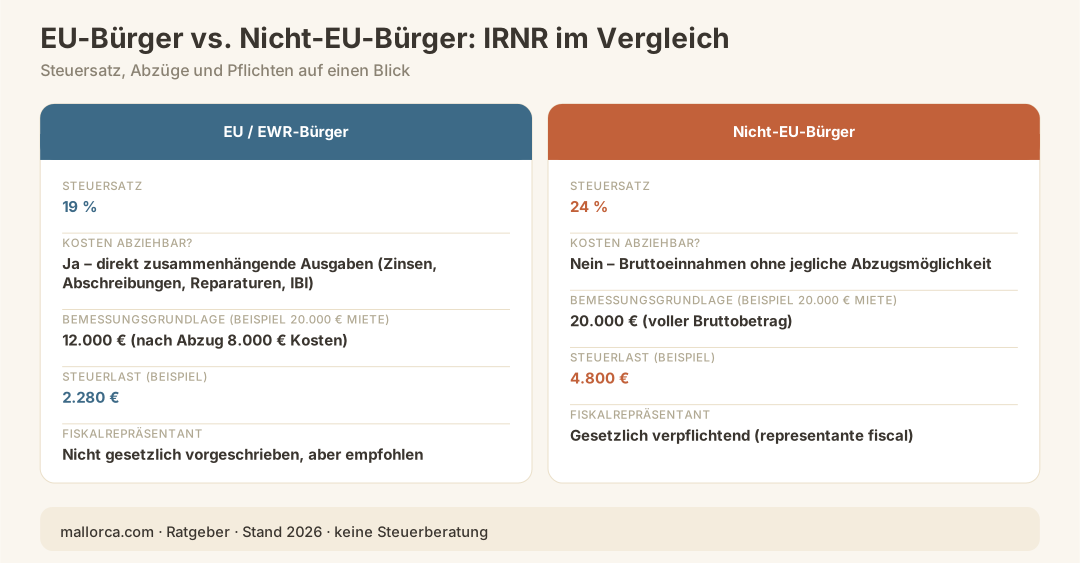
Anyone who rents out a property – whether long-term or as a holiday let – must pay tax on the rental income actually received. A key distinction applies here between EU and non-EU citizens:
EU/EEA citizens may deduct expenses directly related to the rental income (interest, depreciation, repairs, management costs, IBI) and pay tax only on their net income.
Non-EU citizens must pay tax on their gross income without any deductions.
Item
EU/EEA owners
Non-EU owners
Gross rental income
€20,000
€20,000
Deductible costs (e.g. €8,000)
− €8,000
not deductible
Taxable amount
€12,000
€20,000
Tax (19% / 24%)
€2,280
€4,800
Case 3: Capital gain on sale
When a Spanish property is sold, IRNR is payable on the capital gain (sale price minus acquisition costs, including purchase-related costs). In this case, the buyer is legally obliged to withhold 3% of the purchase price and pay it directly to the AEAT as an advance payment towards the seller’s tax. If the actual tax liability is less than this 3%, the seller can claim back the difference; if it is higher, the seller must pay the balance. The return is also filed using Modelo 210, within three months of the end of the buyer’s one-month deadline – so approximately four months after the sale.
2026 tax rates at a glance
Country of residence
Tax rate
Can expenses be deducted?
EU or EEA country (e.g. Germany, Austria)
19%
Yes (for rental income)
Countries outside the EU/EEA
24%
No
Note on Switzerland: Switzerland is neither an EU nor an EEA member. Whether Swiss nationals resident in Switzerland can claim the 19% rate or the 24% rate depends on their individual tax classification. If in doubt, consult a tax adviser with cross-border expertise.
Modelo 210: What you need to file
Modelo 210 is the only form for IRNR. It covers all three types of income (owner-occupation, rental income and sale proceeds), each with different codes and supporting documents. You can file it online through the AEAT portal; electronic filing generally requires a Spanish digital certificate (electronic certificate) or an authorised tax adviser.
Required information and documents:
Documents
Purpose
NIE number (Número de Identificación de Extranjero)
Required for every tax return in Spain
IBI bill showing the cadastral value and cadastral reference
Basis for calculating Renta Imputada
Tenancy agreements / proof of payment
For rental income
Purchase contract (Escritura)
On sale
Tax identification number from your home country
Relevant for double taxation agreements
Certificate of tax residence from your home country's tax authority
Proof of non-resident status
If you don't yet have an NIE number, you'll find everything you need to know in our guide to getting an NIE number on Mallorca.
2026 deadlines: the dates you need to know
The Spanish tax system has no grace periods or automatic extensions. If you file late, you'll pay a penalty – even if you're only a few days overdue.
Type of income
Deadline
Notes
Owner-occupation / notional income (tax year 2025)
31 December 2026
Annual return; relates to the previous year
Rental income, reported individually or together
1–20 April of the following year
Applies to income from 2026 onwards; individual returns for April to September 2026 are still due in July and October 2026 respectively
Capital gain from the sale of a property
3 months after the Modelo-211 deadline (around 4 months after the sale)
The buyer withholds 3% as an advance tax payment
Wealth tax return (tax year 2025)
3 April – 30 June 2026
Separate form Modelo 714
Please note: Under Orden HAC/623/2026, rental income from 2026 onwards has a single filing period: from 1 to 20 April of the following year, whether you declare each receipt separately or report the year’s income together.
Double taxation: What the Germany–Spain tax treaty covers
Germany and Spain have signed a double taxation agreement (DBA). This means you do not pay tax twice in full on the same income. As a rule, income from property is taxed according to the situs principle – the right to tax it belongs to the country where the property is located: Spain. Germany may, however, take the income into account under the progression clause to increase the German tax rate on your other income.
What this means for you in practice:
The IRNR paid in Spain is generally credited against German tax, or the Spanish income is exempted.
You must still declare the Spanish income on your German tax return.
The precise treatment depends on your individual circumstances – a tax adviser with cross-border expertise is essential.
Wealth tax (Impuesto sobre el Patrimonio): Don’t forget it
In addition to IRNR, non-residents who own property in Spain may also be liable for wealth tax (Impuesto sobre el Patrimonio, IP). This is declared separately on Modelo 714.
Importantly, in judgments 1372/2025 of 29 October 2025 (case no. 4701/2023, ECLI:ES:TS:2025:4849) and 1402/2025 of 3 November 2025 (case no. 7626/2023, ECLI:ES:TS:2025:4846), the Tribunal Supremo ruled that allowing only residents to benefit from the combined tax ceiling under Art. 31.Uno of the Wealth Tax Act was discriminatory and unjustified. The wording of the law has not changed, but the restriction is no longer applied: the Ministry of Finance removed it from the Modelo 714 form through Orden HAC/277/2026 (from the 2025 tax year onwards), followed by Orden HAC/652/2026 for the solidarity tax on large fortunes.
The rule limits income tax and wealth tax combined to 60% of the sum of the income tax bases, although wealth tax may be reduced by no more than 80%. Neither the judgments nor the regulations governing the forms explain how to calculate that reference amount for a non-resident who is subject to IRNR rather than IRPF in Spain. It must be calculated case by case by a tax adviser. For previous years, the ceiling can be claimed by applying to amend your self-assessment (Art. 120.3 of the Ley General Tributaria); the limitation period is four years.
The filing period for the 2025 wealth tax return runs from 3 April to 30 June 2026.
Liability and fiscal representatives: who has your back
Non-residents from third countries (outside the EU/EEA) are legally required to appoint a fiscal representative (representante fiscal) resident in Spain to act as their contact with the Spanish tax authorities. EU citizens are not formally required to appoint a fiscal representative, but doing so is common and recommended practice: a locally based tax adviser (asesor fiscal) knows the deadlines, exceptions and latest changes – and helps protect you from liability.
Note: If a tenant resident in Spain pays rent to a non-resident, they may be required in certain cases to withhold part of the rent as tax and pay it to the tax authorities. That is another reason why communication between tenant, landlord and tax adviser should be well coordinated.
The most common non-resident tax mistakes
In practice, the same mistakes crop up time and again. Here are the most serious:
Mistake
Consequence
Failing to declare personal use because “I’m not renting it out”
Back taxes + surcharges for previous years
Using the wrong percentage of the cadastral value (2% instead of 1.1%)
Overpayment or an incorrect tax return
Missing the 31.12. deadline because no payment reminder arrives
Late-payment surcharge and, for a prolonged failure to file, substantial penalties
A non-EU citizen tries to deduct expenses
Incorrect tax return and back taxes
No NIE number
Unable to file Modelo 210
Forgetting to claim the DBA exemption in Germany
Double taxation or trouble with the German tax office
Using the cadastral value from an old notice instead of the current IBI notice
Incorrect basis for calculation
What comes next? The most important related topics
Once you have your non-resident tax affairs in order, these are the next points to clarify:
Consider residency: If you spend more than 183 days in Spain, you automatically become a tax resident, regardless of your intentions. Read what this means in the guide Taxes as a resident (IRPF).
Health insurance: If you are a non-resident without Spanish social security cover, you need private insurance. Find out more in the guide Health insurance in Spain.
Holiday rentals: If you want to earn rental income, you need to check the licensing requirements as well as your IRNR obligations. Rules in the Balearic Islands have become stricter in recent years.
Checklist: File Modelo 210 correctly
Go through this list before filing your return or asking your tax adviser to file it:
NIE number obtained and valid
Current IBI bill obtained, showing the cadastral value and cadastral reference
Tax status checked: non-resident status confirmed (stay < 183 days)
Type of income identified (personal use / rental / sale / combination)
Correct percentage for imputed income determined (1.1% or 2%)
Correct tax rate applied (19% EU/EEA or 24% non-EU)
If renting out the property: rental receipts and deductible expenses documented (EU/EEA)
Deadline noted and added to your calendar
German tax adviser informed of Spanish income (progression clause)
Bank details provided for the tax payment by direct debit, or bank transfer prepared
If selling a property: buyer's 3% withholding documented
Conclusion
Spain’s non-resident tax is not a large amount, but ignoring it can have real consequences. The combination of having to take the initiative, calculating the tax yourself and meeting strict deadlines makes it one of the most common sources of avoidable fines for German property owners in Mallorca. The good news: once you have a working system in place — a local tax adviser, your NIE to hand and each year’s IBI bill on file — you can complete Modelo 210 in minutes or delegate it entirely.
For more complex situations (holiday rentals, a sale, a high-value property or a move to residency), it is always worth getting individual advice.
Official sources
AEAT (Agencia Estatal de Administración Tributaria) – information on IRNR and filing Modelo 210 online: https://www.agenciatributaria.es
Non-Resident Income Tax Act (LIRNR) – published in the BOE: https://www.boe.es
Tribunal Supremo rulings 1372/2025 and 1402/2025 (the shared maximum limit also applies to non-residents) — the doctrine is reproduced verbatim in the preamble to Orden HAC/652/2026: https://www.boe.es/eli/es/o/2026/06/26/hac652
This guide provides a general overview of the legal position and does not replace legal or tax advice on your individual circumstances. Laws and deadlines may change; the linked official sources are authoritative.
Do I have to file Modelo 210 even if I never rent out my Mallorca property?
Yes, absolutely. Spain taxes a form of notional income (*Renta Imputada*) on properties used by their owners, calculated on the basis of the cadastral value. This applies whether or not you receive any rental income. The deadline for the 2025 tax year is 31 December 2026.
How much non-resident tax does a German property owner pay?
As an EU citizen, you pay 19% on the taxable amount. If you use the property yourself, this is often only a few hundred euros a year, depending on its cadastral value. If you rent it out, EU citizens can deduct directly related expenses and pay tax only on the net income.
What happens if I do not file Modelo 210, or file it late?
The Spanish tax authority does not send reminders. If you miss the deadline, you will have to pay late-filing surcharges on the tax owed. If you leave it for longer, the tax authority may open formal proceedings, with much higher penalties than if you file voluntarily.
What is the difference between EU and non-EU citizens under IRNR?
EU and EEA citizens pay 19% and, when renting out a property, can deduct directly related expenses from their rental income. Non-EU citizens pay 24% on gross rental income, with no deductions. They must also generally appoint a tax representative in Spain.
How do I find the correct cadastral value for my property?
You can find the current cadastral value (*Valor Catastral*) and cadastral reference on your annual IBI bill (Spanish property tax). Alternatively, you can look them up through the Sede Electrónica del Catastro.
As a Mallorca property owner, do I also have to pay wealth tax?
That depends on the total value of your assets located in Spain. If it exceeds a certain tax-free allowance, wealth tax (*Impuesto sobre el Patrimonio*) may be due and must be declared separately using Modelo 714. In 2025, the Supreme Court confirmed that non-residents may use the same maximum tax liability rule as residents, which can mean substantial tax savings in some cases.
Can I file Modelo 210 myself, or do I need a tax adviser?
You can file through the AEAT portal, but you will need a Spanish digital certificate and a good understanding of the system. Many owners manage to file themselves in straightforward cases (a single property used only by its owner). If you rent out or sell a property, own multiple properties or have a complex tax position, it is advisable to use a local *asesor fiscal*.
How is non-resident tax treated in Germany?
Spain has the primary right to tax property located in Spain. Germany generally exempts this income from German tax but takes it into account under the progression clause: your Spanish income increases the German tax rate applied to your other income. You should therefore adjust your German tax returns accordingly.
is spain charging 100% property tax?
No. A draft law proposes an additional levy of up to 100% on purchases of residential property by non-EU non-residents. As of May 2026, it had not been passed. The proposed levy is neither an annual property tax nor the non-resident tax (IRNR) described here. This is not legal or tax advice.
We use cookies to provide you with the best possible experience on our website. Learn more in our Privacy Policy