
Hipoteca Joven Mallorca: how IBAVI enables a 100% mortgage
If you're young, live in Mallorca and finally want to buy a home of your own, you face a seemingly impossible problem: Property prices on the island are among the highest in Spain, and standard bank mortgages cover no more than 80% of the purchase price. For many, finding the remaining 20% plus purchase costs from their own savings is simply impossible. That's where the Hipoteca Joven Mallorca comes in: The IBAVI (Institut Balear de l'Habitatge) guarantees up to 20% of the purchase price, allowing the bank to finance up to 100% — without you having to provide a deposit from your own funds. At national level, first-time buyers may also be eligible for the Aval ICO guarantee. This guide explains how both schemes work, what requirements you need to meet, which tax benefits are available on top and how to approach the process step by step — with all the specific figures supported by the research.

Mortgage calculator
Explanation
The loan amount is the capital originally granted. The preset is arithmetically consistent with the selected loan-to-value share of the example purchase price.
Explanation
These are this calculator’s three modelling paths, not a statutory product classification: a fixed rate, index plus margin, or a fixed phase followed by a variable phase.
Explanation
TIN (tipo de interés nominal) is the nominal annual interest rate before costs; TAE (tasa anual equivalente) includes costs and payment timing and does not belong in this field. The preset is a round worked example, not a market rate.
Explanation
The total term determines the number of monthly payments. The preset is a worked example.
- Monthly payment (cuota)
- €1,280.37
Why this figure?
The cuota is the regular monthly payment of interest and principal under the French annuity system.
Model calculation: twelve equal months, first payment one month after disbursement, no stub period and the calculator’s own cent rounding. The bank schedule can differ because of its day-count convention, stub period and rounding. The controlling documents are the FEIN (European Standardised Information Sheet containing the binding loan information) and the escritura (notarial loan deed).
Legal status: 1 January 2023
This calculation is provided for guidance only and is not a substitute for tax or legal advice in specific cases.
What is the IBAVI's Nova Hipoteca Jove?
The Nova Hipoteca Jove is not a direct government loan — the IBAVI does not pay you any money. Instead, the scheme provides a public guarantee (Garantía) to the lending bank. This guarantee covers the portion of the purchase price a bank would not normally finance: up to 20% for buyers under 40, as well as large families, single parents and people with disabilities. For all other eligible applicants, the guarantee is up to 15%.
This allows the bank to offer a mortgage covering up to 100% of the purchase price — provided its own lending criteria permit it. In practice, banks currently offering mortgages under this scheme include CaixaBank, Colonya Caixa d'Estalvis de Pollença and Cajamar Caja Rural.
Note: The IBAVI guarantee is not a free pass — the bank will still assess your creditworthiness, income and ability to meet the repayments. No guarantee will be granted without a positive lending decision from the bank.
| Feature | Details |
|---|---|
| Scheme name | Nova Hipoteca Jove |
| Administered by | IBAVI (Institut Balear de l'Habitatge) |
| Type of scheme | Public guarantee to the bank |
| Maximum purchase price (including parking space, cellar, etc.) | €382,744.84 |
| Guarantee for buyers under 40 / special groups | up to 20% of the purchase price |
| Guarantee for all other eligible applicants | up to 15% |
| Minimum/maximum mortgage | from 80% to 100% of the purchase price |
| Guarantee term | until the guaranteed amount has been repaid |
| Processing fee | 0.50% of the guaranteed amount (one-off) |
| Partner lenders (March 2025) | CaixaBank, Colonya Caixa Pollença, Cajamar |
Who is eligible for the programme? The IBAVI requirements in detail
Personal requirements
For IBAVI to approve your guarantee, you must meet all the following requirements:
- Nationality / residency: Spanish or EU citizenship, or legal residence in Spain.
- Residence in the Balearic Islands: At least 5 years of residence on the islands, either continuous or cumulative.
- No other residential property in Spain — with a few exceptions (an inherited share, loss of property ownership due to divorce, a disaster, domestic violence, terrorist attacks, or a disability where the existing property is not accessible).
- Income limits (gross annual income):
| Household size | Maximum annual income |
|---|---|
| 1 person | €60,666.65 |
| 2 or more people | €68,250.00 |
- Age limit for the 20% guarantee: under 40 years old. Older applicants who meet all other criteria can receive a maximum of 15%.
Property requirements
- Located in the Balearic Islands (Mallorca, Menorca, Ibiza, Formentera)
- Used as a permanent main residence (primera residencia habitual y permanente)
- Purchase price including outbuildings (garage, cellar) maximum €382,744.84 — excluding additional costs and taxes
Important: The old price cap was €270,000. The increase to €382,744.84 was announced in March 2025 and gives significantly more buyers in Mallorca access to the programme.
The Aval ICO: The national counterpart to the IBAVI programme
Alongside the regional IBAVI programme, there is the national Aval ICO (Instituto de Crédito Oficial), which also guarantees up to 20% of the purchase price — or up to 25% for properties with an energy rating of A to D.
According to our research, this guarantee was available until 31 December 2025. At the time of writing, it had not yet been definitively confirmed whether or how it would continue in 2026 — check directly with the ICO or your bank for the latest information.
| Feature | Aval ICO |
|---|---|
| Standard guarantee amount | up to 20% |
| Guarantee amount for energy ratings A–D | up to 25% |
| Guarantee term | up to 10 years |
| Age limit | up to 35 years old (no limit if there are minors in the household) |
| Maximum gross annual income | €37,800 |
| Residence in Spain | at least 2 years of legal residence |
| Purpose | First main residence |
Note: The IBAVI guarantee and Aval ICO are alternative, not cumulative programmes — as a rule, you can only use one of them for the same transaction. Because the IBAVI guarantee has much higher income limits and is tailored to the Balearic market, it is the more attractive option for many buyers in Mallorca. Ask your bank and a financial adviser to work through both scenarios with you.
ITP exemption and tax benefits: How much could you really save?
Transfer tax (ITP)
Explanation
The taxable base (base imponible) is the value used to calculate the tax: the price stated in the deed or the higher cadastral reference value. Enter the higher value.
Explanation
A main home (vivienda habitual) is the home you normally occupy under Spanish income tax rules. Select a profile only if you meet all its conditions; the calculator checks the value threshold and transaction date.
The general tariff applies without personal tax relief, for example when buying a second home.
- Property transfer tax (ITP) payable
- €25,600.00
Legal status: 14 June 2026
This calculation is provided for guidance only and is not a substitute for tax or legal advice in specific cases.
In addition to the mortgage guarantee, the Balearic Islands have a tiered system for Impuesto sobre Transmisiones Patrimoniales (ITP), the equivalent of property transfer tax on resale properties. On a purchase costing several hundred thousand euros, it is often the largest single additional expense.
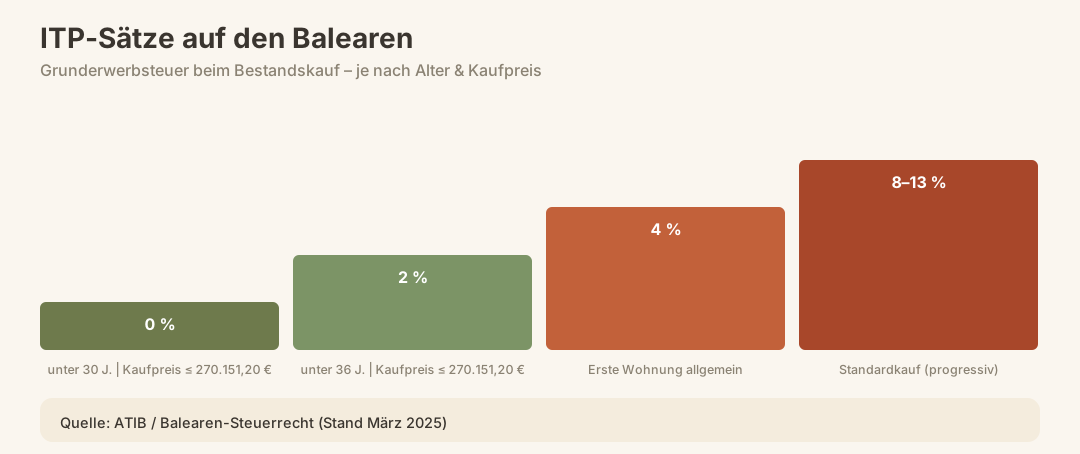
| Buyer category | ITP rate | Conditions |
|---|---|---|
| Under 30 | 0% (full exemption) | Purchase price ≤ €331,859.70, relief on the first €270,151.20; acquisition of at least 50% of the full ownership of this first home and no other property in which you own 50% or more; annual income ≤ €52,800 (individual) or €84,480 (joint); mortgage ≥ 60% of the appraised value; resident in the Balearic Islands for at least 3 years |
| Under 36 | 2% (reduced rate) | Purchase price ≤ €331,859.70, reduced rate on the first €270,151.20; purchase of at least 50% of the full ownership; no other residential property ownership |
| Large and single-parent families | 2% (reduced rate) | The property becomes the main residence of the parent or parents living with their children; purchase of at least 50% of the full ownership, with no other property in which they own 50% or more. Value limit since 14 June 2026: the amount applicable to the island, increased by 15% (Mallorca and Menorca: €331,859.70 plus 15%). The 2% rate applies to the first €270,151.20; the remainder is taxed at 8%. For single-parent families in the general category, the limit remains €270,151.20 |
| First home – general category | 4% (reduced rate) | Purchase of at least 50% of the full ownership as a first main home; the above conditions are not met |
| Standard purchase (no relief) | 8–13% progressive | Standard Balearic rate schedule |
Note: The ITP eligibility threshold for the special rates has been €331,859.70 (Mallorca and Menorca) since 14 June 2026. However, the relief itself applies only to the first €270,151.20; the remainder is taxed at the standard rate. Neither threshold is the same as the IBAVI purchase price limit of €382,744.84. If the purchase price falls between these two amounts, you can benefit from the IBAVI guarantee, but no longer qualify for the full ITP exemption or the 2% rate.
For a full breakdown of the additional costs of buying, see our guide to property purchase costs in Mallorca.
Direct grant: €10,000 per property
In addition to tax relief and mortgage guarantees, the Balearic government offers a direct grant of €10,000 per property. Applicants must be aged 40 or under, have lived continuously in the Balearic Islands for the five years immediately before applying, and have bought a property on the islands on or after 1 January 2026 – either an existing property or one under construction. The property must be your main residence for at least five years. If two people buy together, the grant is divided according to their ownership shares. Applications have been open since 17 July 2026 and will be accepted until 31 December 2027 or until the budget is exhausted, on a first-come, first-served basis.
Important: This direct grant is subject to specific income and purchase price limits and requires a separate application. It can be combined with the IBAVI guarantee, but not necessarily with all other forms of support at the same time. Before buying, check the current rules on combining support with an authorised advisory service or a gestor.
Bank products: what the partner banks actually offer
The IBAVI scheme is available only through accredited partner lenders. As of March 2025, these are CaixaBank, Colonya Caixa d'Estalvis de Pollença and Cajamar Caja Rural. Other banks offer their own mortgages for young buyers with higher loan-to-value ratios, but without an IBAVI guarantee these generally top out at 90–95%.
For example, Imagin (a CaixaBank subsidiary) offers financing under the Balearic Islands scheme of up to 90% of the lower of the purchase price and the valuation, with a discounted fixed rate of 2.85% NIR (3.574% APR) if you have your salary paid into the account and take out home and life insurance; without these conditions, the rate is 3.60% NIR (4.084% APR). These terms may change — treat them as a guide, not as binding offers.
| Bank | Maximum financing (scheme) | Key detail |
|---|---|---|
| Colonya Caixa Pollença | up to 95% generally; 100% for under-40s / large families / people with disabilities | IBAVI guarantee required |
| CaixaBank / Imagin | up to 90% (Imagin product with IBAVI) | Discounted fixed rate |
| Cajamar Caja Rural | Participates in the scheme | Terms available on request |
| BBVA (not an IBAVI partner) | up to 95% (its own Hipoteca Joven) | Without an IBAVI guarantee |
Step by step: how to apply for an IBAVI guarantee and a mortgage
Check your eligibility: Age, proof of income (IRPF returns from recent years), registered residence (Empadronamiento) in the Balearic Islands for at least 5 years, and no ownership rights in other properties in Spain.
Choose a property: Purchase price ≤ €382,744.84 (including garage/basement), located in the Balearic Islands, and intended as your permanent main residence.
Have the land registry entry checked: Before signing a reservation agreement, check the Nota Simple from the Registro de la Propiedad for charges, mortgages and planning status. More on this: Checking the land registry in Spain.
Sign a reservation agreement: Typically with a deposit of 1% to 3% of the purchase price. Details: Reservation agreements in Spain.
Submit a mortgage application to an IBAVI partner bank: DNI/NIE, recent IRPF tax returns, an employer’s certificate or proof of income for self-employed applicants, the property’s Nota Simple, and a valuation (tasación) — the bank will arrange this.
Apply for the IBAVI guarantee: This is usually handled through the lender alongside the mortgage application. Processing fee: 0.50% of the guaranteed amount (a one-off payment by the buyer).
Arras agreement (preliminary contract): Once the mortgage is approved, a private purchase agreement (contrato de arras) is signed, usually with a 10% deposit.
Notary and Escritura Pública: The purchase is formalised before a notary, and the mortgage is registered. More on the process: Buying property: the legal process.
Pay ITP and register the property: Declare ITP (at a special rate or with an exemption, if applicable) to ATIB (Agència Tributària de les Illes Balears) within 30 days of signing before the notary.
Apply for the direct grant: If you meet the conditions, apply separately for the €10,000 grant from the Conselleria de Vivienda, Territorio y Movilidad (online at adquisiciohabitatge.caib.es).
Note: IBAVI address: C/ de Manuel Azaña, 9, Palma. Tel.: 900 700 003. Website: ibavi.caib.es
Worked example: what the IBAVI guarantee means in practice
Let’s take a 30-year-old buyer with an annual income of €38,000 who wants to buy a flat in Palma for €280,000 (an existing property).
| Item | Amount |
|---|---|
| Purchase price | €280,000 |
| Mortgage (100% thanks to the IBAVI guarantee) | €280,000 |
| IBAVI guarantee (20%) | €56,000 |
| Mortgage financing (80% directly) | €224,000 |
| IBAVI processing fee (0.50% of €56,000) | €280 |
| ITP (age 30, so the 0% rate does not apply: 2% on the first €270,151.20, 8% on the remainder) | €6,190.93 |
| Notary + Land Registry (indicative estimate, not guaranteed) | approx. €2,000–3,000 |
| Cash needed for purchase costs | approx. €8,500–9,500 |
Without the IBAVI guarantee, the same buyer would have needed €56,000 for the deposit with 80% financing, plus approx. €9,000 in purchase costs — around €65,000 in total. The guarantee reduces this to the purchase costs alone.
Important: The buyer in this example is 30 years old, so she no longer qualifies under the rule for under-30s. She pays the reduced rate of 2% on the first €270,151.20 and 8% on the remainder. If she were under 30 and met all the other requirements, no ITP would be due on the first €270,151.20; only the remaining €9,848.80 would be taxed at 8%, or €787.90. Since 14 June 2026, this has applied to purchase prices of up to €331,859.70 on Mallorca (Ley 4/2026).
Most common mistakes with the Hipoteca Joven on Mallorca
1. Confusing the limits for the ITP tax relief and the IBAVI guarantee. On Mallorca, the ITP tax relief for under-30s and under-36s applies to purchase prices of up to €331,859.70 and affects only the first €270,151.20; the remainder is taxed at 8%. By contrast, the IBAVI purchase-price limit is €382,744.84. Buyers purchasing for between €331,859.70 and €382,744.84 lose the ITP tax relief entirely but can still use the IBAVI guarantee.
2. Proof of residence is missing or incomplete. The IBAVI guarantee requires 5 years’ residence in the Balearic Islands. Recent arrivals do not qualify — even if they backdate their address registration.
3. Applying for both the ICO and IBAVI guarantees. The 2 guarantees cannot be combined for the same transaction. Applying for both risks having 1 or both applications rejected.
4. Tasación (valuation) too low — leaving a funding gap. The guarantee covers up to 20% of the purchase price, not the valuation. If the tasación is lower than the purchase price, the bank will finance no more than 100% of the valuation. You must cover the difference between that and the purchase price from your own funds.
5. Failing to apply separately for the direct grant. The €10,000 direct grant is not applied for automatically with the mortgage — it requires a separate application to the Conselleria de Vivienda.
6. Already owning a property in Spain (even a half share or one with outstanding debt). Even a small inherited share can make you ineligible for support if none of the exceptions applies.
What happens after the purchase?
Your obligations do not end when you sign before the notary. As a property owner on Mallorca, you will face recurring costs and reporting requirements:
- IBI (property tax): An annual municipal tax based on the cadastral value. Find out more: IBI tax in Spain
- Community of owners: If you buy an apartment, you become a member of the community of owners and must contribute to its costs. Everything you need to know: Communities of owners in Spain
- Wealth tax: Payable in Spain once your assets exceed certain exemption thresholds. Wealth tax in Spain
- Energy performance certificate: Required if you later rent out or sell the property. Energy performance certificates in Spain
- Contents insurance: Often required by the bank. Contents insurance in Spain
If you later want to let the apartment long-term, you’ll find everything you need under Long-term rentals in Mallorca.
Checklist: Am I ready for the Hipoteca Joven & IBAVI guarantee?
- I am under 40 years old (for the 20% guarantee; under 36 for 2% ITP; under 30 for 0% ITP)
- I have been resident in the Balearic Islands for at least 5 years in total
- My gross annual income is below €60,666.65 (as an individual) or €68,250 (as a couple)
- I do not own another property in Spain (or I qualify for an exception)
- The purchase price, including a parking space, is no more than €382,744.84
- The property is in the Balearic Islands and will become my permanent main residence
- I have approximately €8,000–12,000 available to cover additional costs (ITP, notary, land registry and fees)
- I have filed my IRPF tax returns for previous years in full with the AEAT
- I have contacted one of the partner banks (CaixaBank, Colonya, Cajamar)
- I have checked whether I qualify for the direct grant (€10,000)
Conclusion
IBAVI’s Nova Hipoteca Jove is one of Spain’s most substantial and well-funded home-buying programmes for young people. The increased purchase-price limit of up to €382,744.84 now makes the programme accessible across a much larger share of the Mallorca market than before the 2025 reform. Combined with the ITP exemption for those under 30 and the potential €10,000 direct grant, it offers a package that genuinely boosts purchasing power — but only if every element is applied for correctly and coordinated with the others.
The biggest pitfall is not eligibility but coordination: anyone who tackles the grant application, tax exemption, IBAVI guarantee and bank financing without professional guidance risks missing out on individual benefits. Before you sign a reservation agreement, have the full breakdown of costs calculated and put in writing.
Official sources
- IBAVI – Nova Hipoteca Jove (programme description and requirements): https://www.caib.es/sites/nova_hipoteca_jove/es/
- IBAVI – Requirements: https://www.caib.es/sites/nova_hipoteca_jove/es/requisitos
- IBAVI main portal: https://ibavi.caib.es
- ATIB – Agència Tributària de les Illes Balears (ITP administration): https://www.atib.es
- ICO – Instituto de Crédito Oficial (Aval ICO): https://www.ico.es
- BOE / BOIB – official gazettes for the legal provisions: https://www.boe.es / https://www.caib.es/boib
- Govern de les Illes Balears – Conselleria de Mobilitat i Habitatge: https://www.caib.es